Roof Damage Insurance Claims in Minneapolis and the Twin Cities Metro
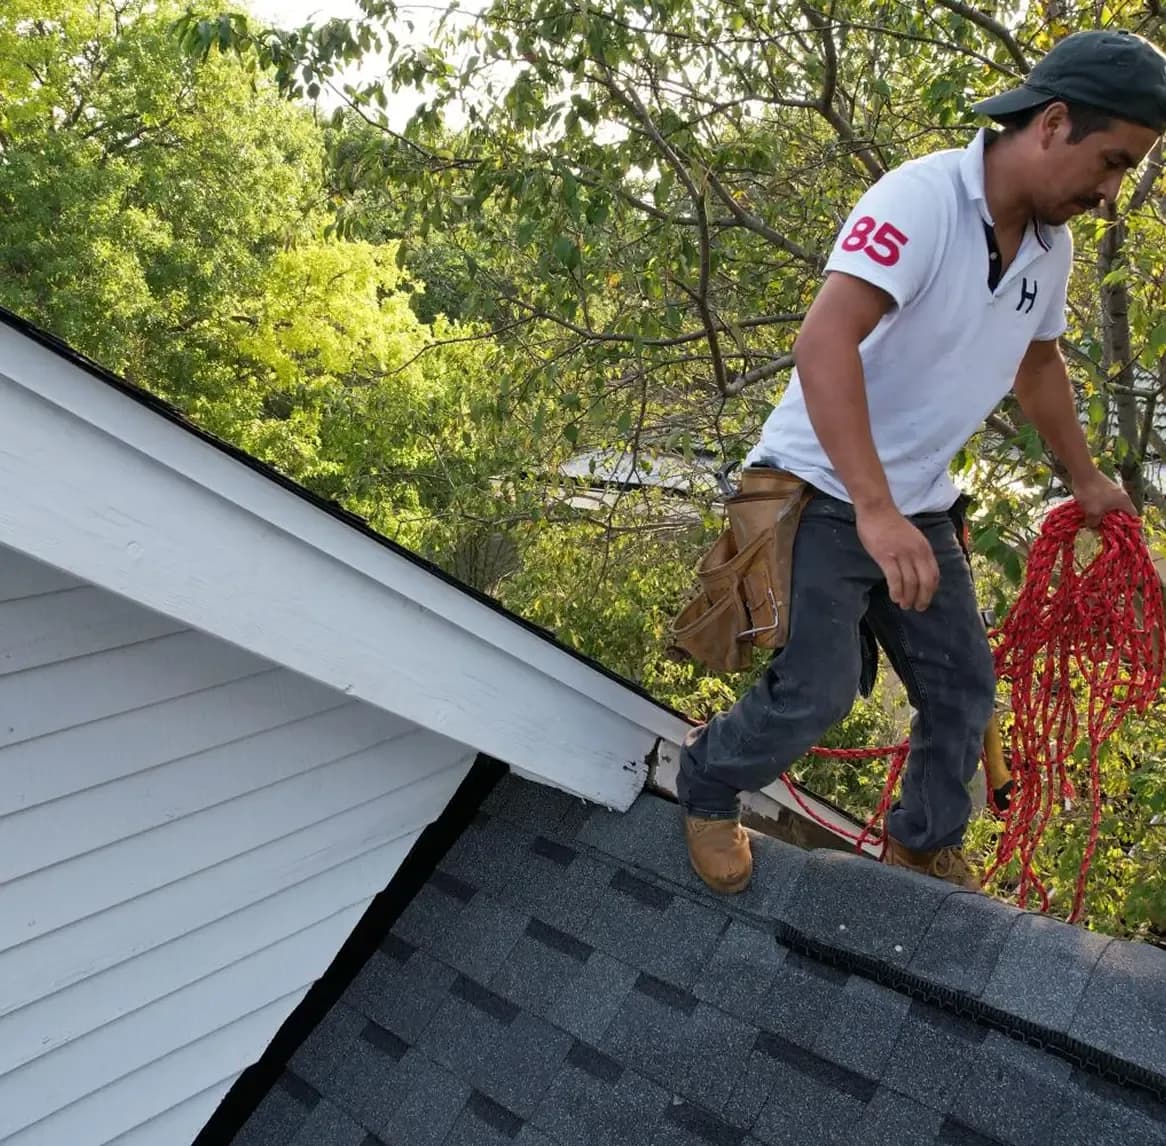
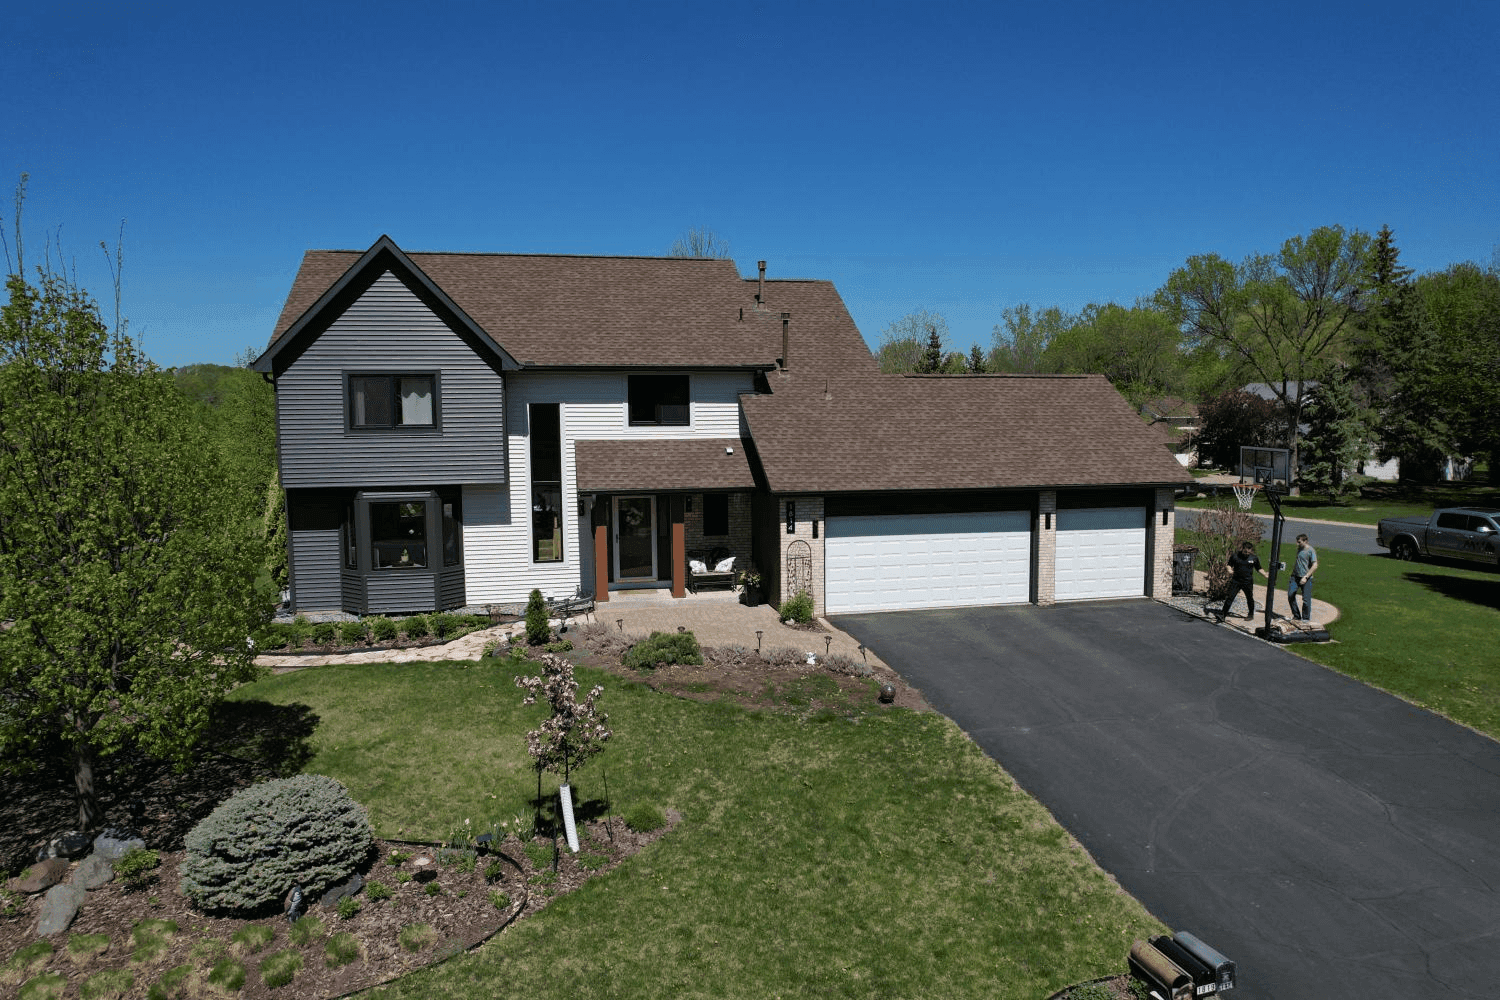
Understanding Your Options After Storm Damage
A bad storm rolls through, and suddenly you’re looking at your roof, wondering what happens next. Do you have enough damage to consider replacement? Does it make sense to involve insurance? Or is this something you’ll ultimately handle out of pocket?
Midwest Construction & Remodeling works with Twin Cities homeowners on both insurance-related and retail roof replacement projects. We can evaluate your roof, explain what a full replacement would involve, and help you understand your options before you decide how to move forward.
What Should You Do If You Think Your Roof Has Storm Damage?
You don’t need to know whether you have an insurance claim before having your roof inspected.
If hail or high winds have you concerned, an inspection will give you a clearer picture of your roof’s condition. From there, you can decide whether an insurance-related replacement or an out-of-pocket project is the more appropriate route.
Midwest approaches those two types of projects differently and has experience helping homeowners navigate either path.
The important part is starting with what your roof actually needs rather than assuming a claim is automatically the answer.
Common Signs of Roof Damage
Some storm damage is easy to spot from the ground, while other problems may not be obvious without a closer inspection. After hail or high winds, keep an eye out for:
Missing, cracked, or broken shingles: High winds and hail can loosen or damage individual shingles.
Granules collecting near downspouts or gutters: Asphalt shingles naturally lose some granules over time, but noticeable loss after a storm can be worth investigating.
Dents or impact marks: Hail may leave visible damage on gutters, vents, flashing, and other exterior components.
Leaks or interior water stains: Water showing up inside the home can indicate that the roofing system has been compromised.
Shingles that look lifted or out of place: Wind can disturb shingles even when they have not completely blown off.
Not every sign means you automatically need a full roof replacement or should file an insurance claim. If something looks different after a storm, an inspection can help you understand the extent of the damage and whether Midwest’s full-replacement services are the right fit.

Roof Insurance Coverage
Types of Roof Damage Typically Covered
Here are common damages usually covered:
- Wind Damage Claims: Strong winds can rip off shingles or hurt the roof’s structure.
- Hail Damage Insurance: Hail can leave dents and cracks in your roof.
- Storm Restoration Services: Some policies help restore roofs after big storms.
Knowing this helps you get ready if severe weather comes.
Exceptions and Exclusions in Policies
Not everything is covered, though. Watch for these:
- Insurance Deductible: You pay this amount first before insurance helps.
- Policy Deductible: Different claims may have different deductibles.
- Exclusions: Many policies don’t cover old wear or maintenance problems.
Read your policy carefully so nothing surprises you later.
Common Causes of Roof Damage
Roofs face lots of risks over time. Here are some usual causes:
- Wind Damage
Strong wind can cause missing shingles or damage the roof frame. Make sure to file wind damage claims fast to fix things sooner. - Hail Damage
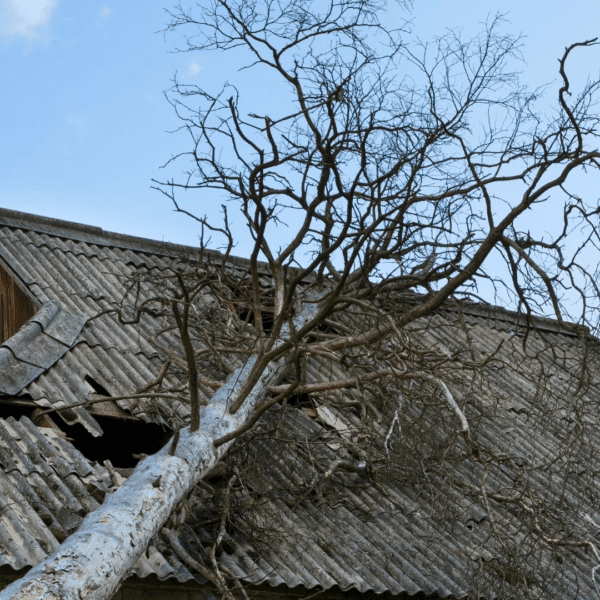
Hailstorms can smash parts of your roof. Hail damage insurance can cover repairs if you report it soon after the storm. - Other Causes (e.g., tree damage, age)
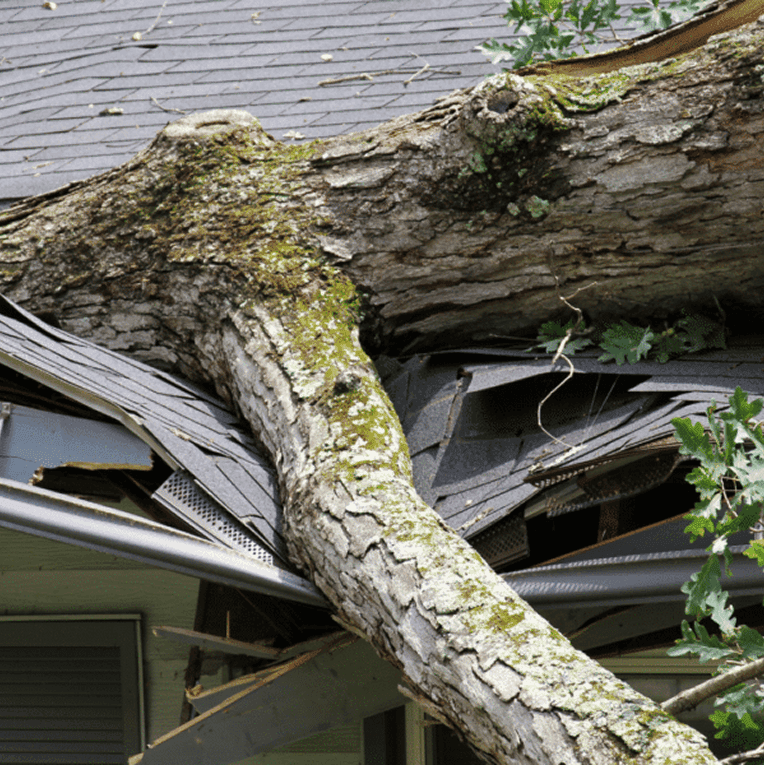
Branches falling during storms or an old roof also cause damage. Storms often make these worse, so watch out.
How Does the Roof Insurance Claim Process Work?
The details of a roof insurance claim depend on your insurer and policy; your insurance company ultimately determines coverage.
From the contractor side, Midwest focuses on the replacement itself. We inspect the roof, develop the project scope, help you select roofing materials, and carry the project through installation and the final walkthrough.
Our process keeps homeowners informed from the initial inspection through production, so they don't have to wonder what happens next.
For roofing measurements, Midwest uses EagleView as part of its process.
Filing a Roof Insurance Claim
Step-by-Step Guide
Filing a roof insurance claim can feel tricky at first. But knowing the steps helps you handle it better. Start by calling your insurance company to report the damage and begin the roofing insurance process. Take clear photos and notes of all the damage you see. This helps when you file a claim.
Midwest Construction & Remodeling makes roofing claims management easier. We guide you on how to file a claim right. Our team provides assistance with insurance claims to ensure you don’t struggle with complex forms or missed deadlines.
After filing, check in with your insurer often. Quick replies cut down delays and keep things moving.
Necessary Documentation
Good paperwork is essential for roofing claims. You need detailed records showing the damage and repair costs. This roofing claim documentation proves what needs fixing.
Midwest Construction & Remodeling gives clients an insurance claim checklist that includes:
- Photos of roof damage from different angles
- Copies of past maintenance or inspection reports
- Repair estimates from licensed contractors
- Filled-out insurance forms
Having these ready makes things go faster, and fewer questions come from adjusters or insurers.
What Roofing Materials Does Midwest Install?
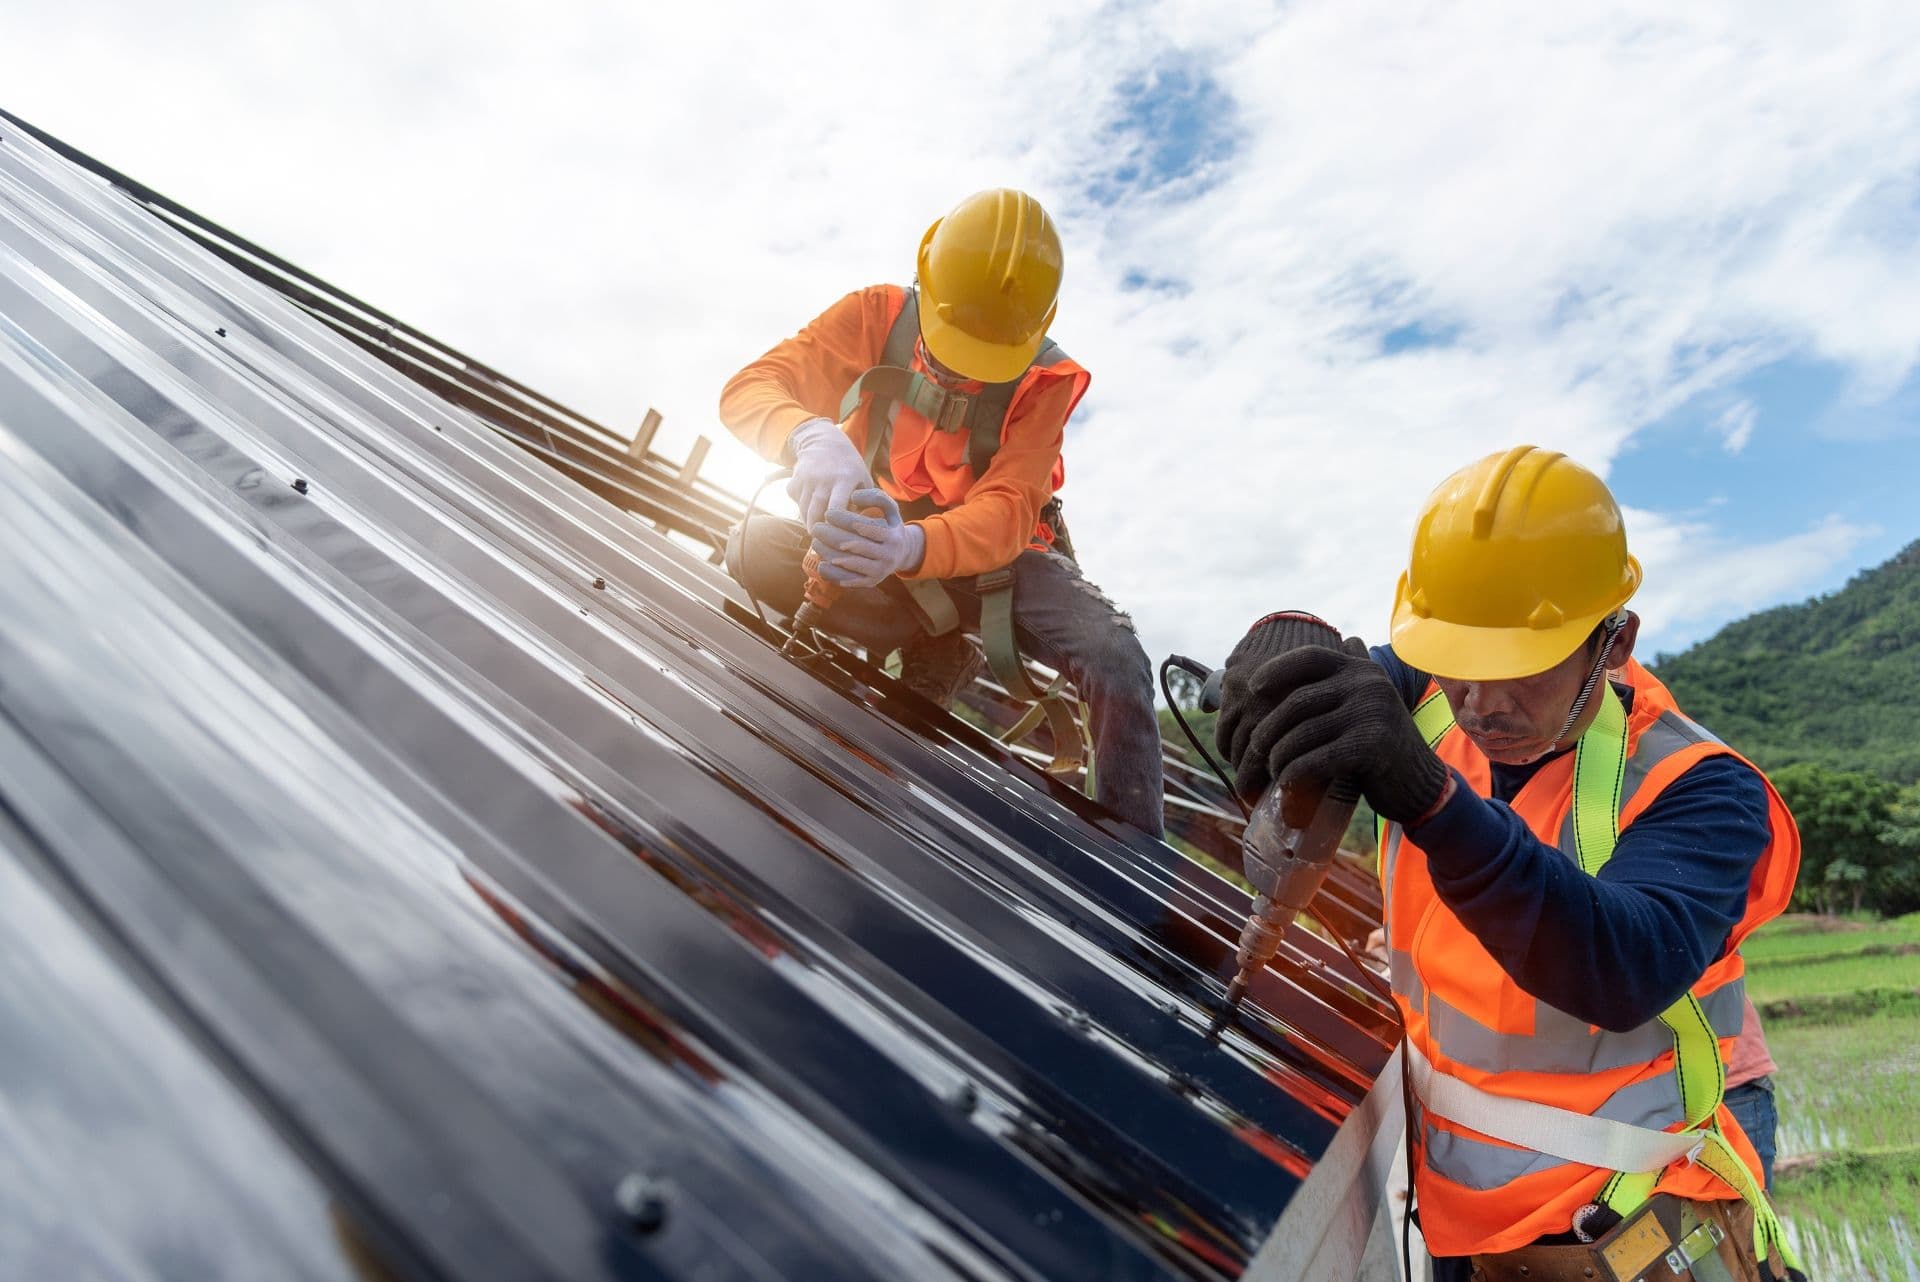
Midwest primarily installs Owens Corning roofing products and can work with other roofing manufacturers when a project calls for it.
Once you know replacement is the right path, you can compare roofing options based on what makes sense for your home rather than simply replacing what was there before.
Midwest emphasizes premium materials and proper installation instead of choosing products or reducing project scope just to reach the lowest possible price.
Working with Insurance Adjusters
What to Expect
Meeting with an insurance adjuster is part of filing a roof insurance claim. The adjuster comes for a roof inspection to see the damage firsthand.
You can anticipate that your roofing contractor will collaborate closely with the adjuster during this time. The roofer helps by explaining the damage clearly and backing up your claim with expert info.
This teamwork helps avoid mix-ups about what repairs are covered and needed.
Preparing for the Inspection
Before the adjuster arrives, gather all your evidence, such as photos and repair quotes. Do a careful roof damage assessment yourself first. That way, you can point out serious problems clearly.
Being ready shows you take things seriously. It can help speed up approval without extra inspections or arguments about damages.
Addressing Concerns
Delays happen when answers are slow or paperwork is missing. To reduce delays in managing claims:
- Reply quickly to questions
- Send extra documents fast
- Keep excellent communication between you, contractors, and insurers.
Staying organized from the beginning to the end helps you avoid common mistakes that can delay repairs and payments.
Midwest Construction & Remodeling's Role in Your Claim
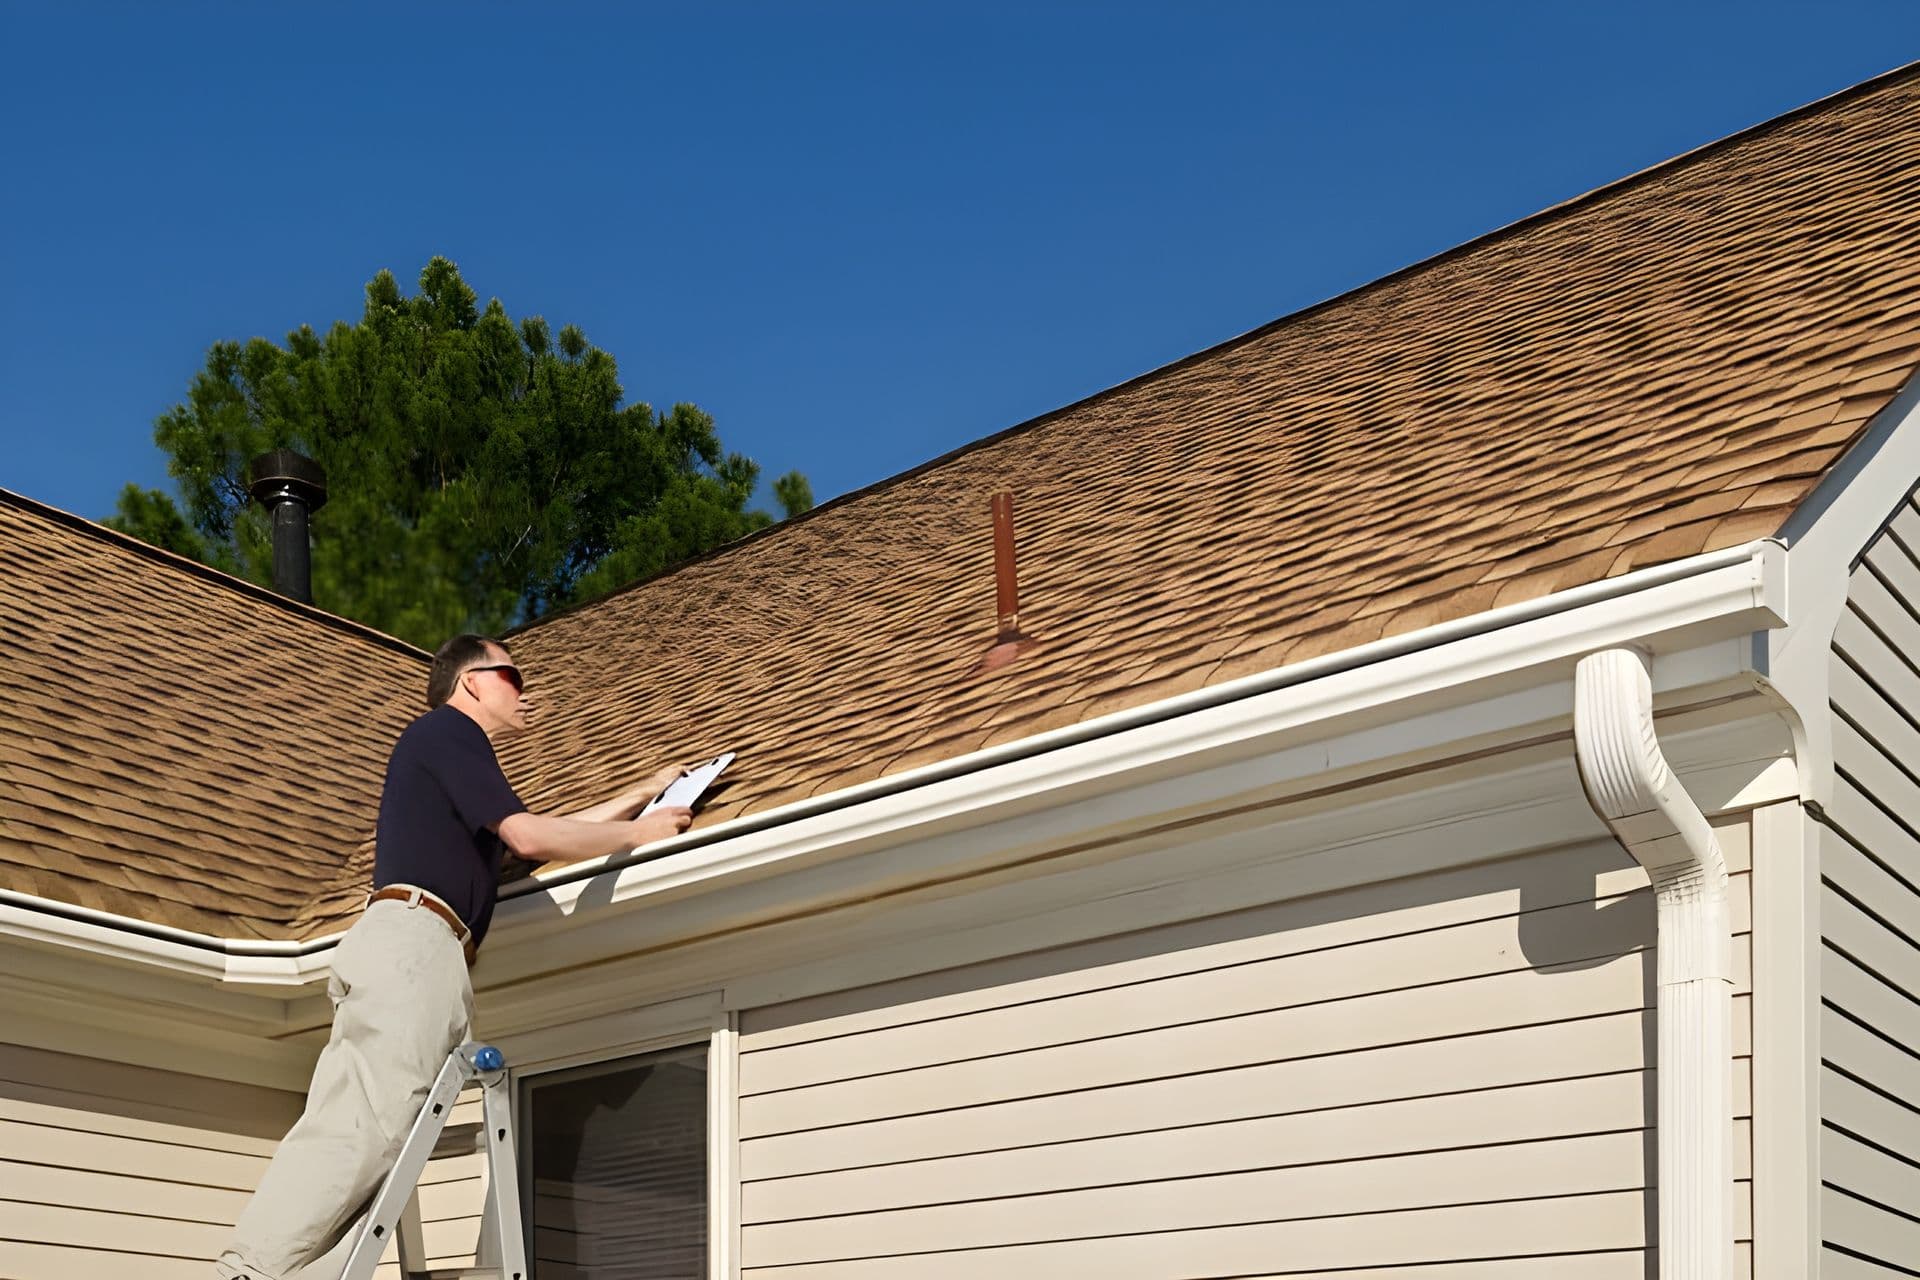
1. Expert Roof Inspections and Damage Assessments
A roofing inspection starts every successful insurance claim. Our team checks your roof carefully to find all damage. To safely obtain precise information, we use aerial roof measurement tools. The information helps us catch problems you might miss from the ground.
We take detailed documentation like photos, notes, and measurements. This proof supports your insurance claim well. Getting a full roofing damage assessment stops delays or denials later on. You can trust our experts to show exactly what’s wrong with your roof so you can move ahead without worry.
- Complete roofing inspection
- Precise roof damage assessment
- Aerial roof measurement for safety
- Photos, notes, and detailed documentation
2. Insurance Coordination
Dealing with insurance can get confusing. We simplify the process by helping you with claims every step of the way. Our team talks with your insurance provider so you don’t have to.
We know local insurance regulations and adjusters’ needs in Minneapolis-St. Paul well. This lets us push for fair settlements on your behalf. Client insurance coordination means less stress for you—we handle paperwork, phone calls, and follow-ups while keeping you updated.
- Simplify the process for you
- Insurance claim assistance.
- Support with client insurance coordination
- Communicate with insurance providers
3. Streamlined Claim Process Support
We strive to simplify your roofing claim from the beginning to the end. Our team manages inspections closely and coordinates steps between contractors and insurers. We document everything carefully so your claim stays strong.
By inspecting damage early and keeping clear records, we avoid errors that slow claims down. This method expedites the approval process and initiates repairs promptly without any unexpected expenses.
We handle each phase—inspection, documentation, communication—with experience. That gives you peace, knowing pros are managing your roofing claim right.
- Streamline every step
- Manage inspections thoroughly
- Coordinate between contractors and insurers
- Document all details clearly.
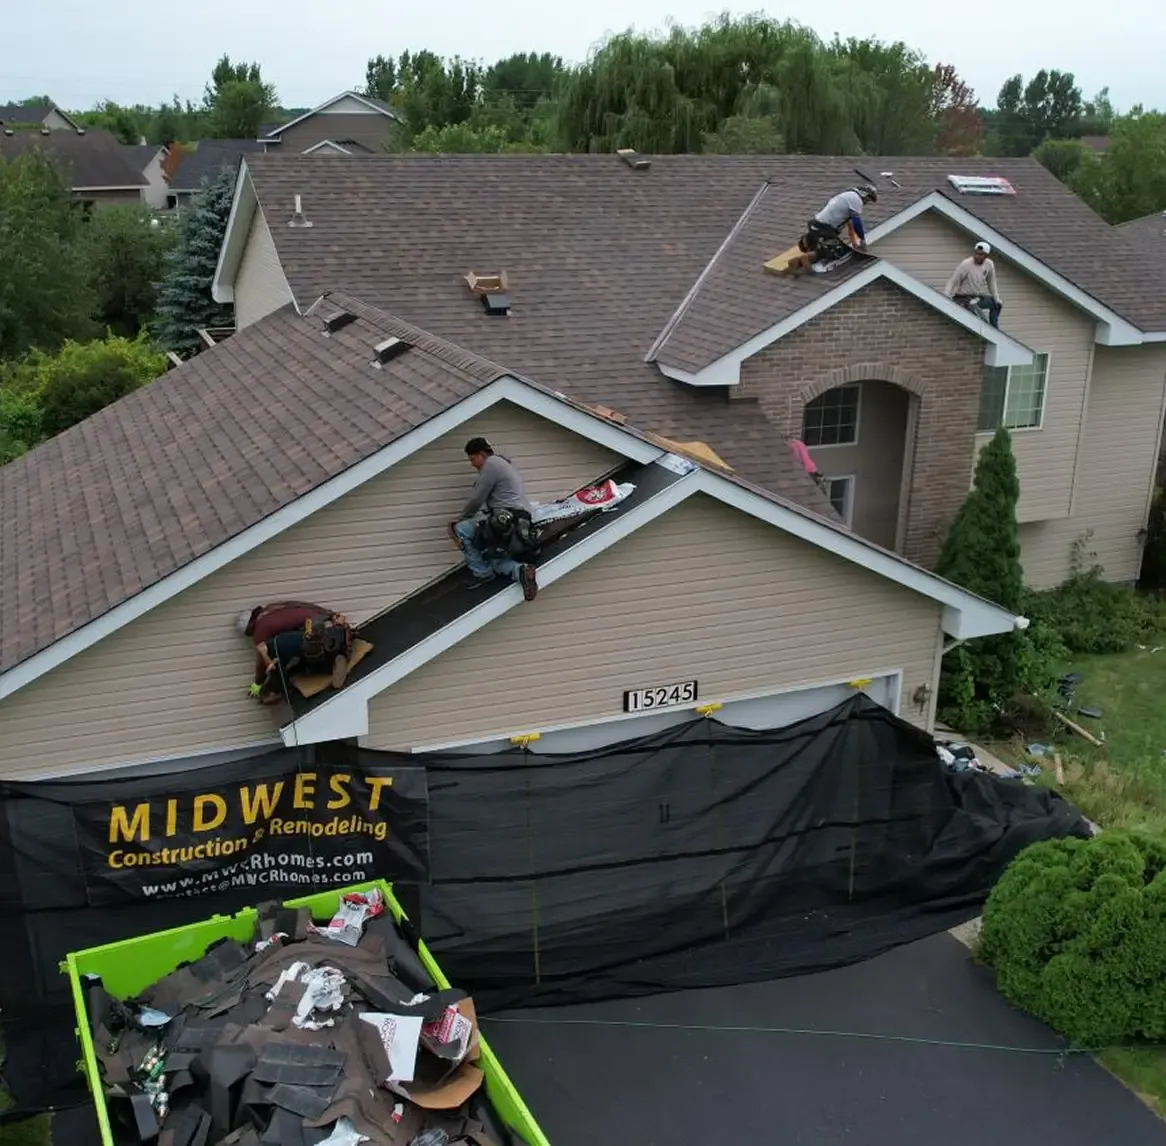
What If You Don’t Use Insurance?
You can still move forward with roof replacement even if the project isn’t being handled through an insurance claim.
Midwest works with homeowners paying directly for replacement as well as those following the insurance route. Flexible payment options are also available for qualifying projects.
Roof Insurance Claim Help Across the Twin Cities Metro
Midwest Construction & Remodeling serves homeowners throughout the Twin Cities Metro, primarily within about 35 miles of our Plymouth location. That includes communities such as Plymouth, Maple Grove, Minneapolis, Minnetonka, and Eden Prairie.
If you’re outside one of those cities but still in the metro area, check our service areas or contact us to see whether your home is within range.
Roof Insurance Claim FAQs
Roofing insurance coordination helps manage your claim with insurers. It keeps the process smooth and reduces delays.
Start by documenting damage with photos and estimates. Then contact your insurer to report the claim. Follow their instructions carefully.
Yes, experts provide claims negotiation assistance. They handle paperwork and communicate with your insurance provider for you.
The adjuster reviews roof damage firsthand. Your contractor may accompany the adjuster to provide explanations and support the claim with detailed information.
Midwest Construction & Remodeling offers expert guidance through every step of roofing claims management in the Minneapolis roofing market, ensuring a stress-free experience with approachable communication and local expertise tailored to the Twin Cities weather impact on roofs.
Hire licensed contractors with favorable reviews. Avoid upfront full payments. Always get written estimates and contracts.
You can appeal claim decisions by providing extra evidence or correcting paperwork errors. Professional help improves appeal success.
Twin Cities weather causes storms that often damage roofs. Local expertise helps identify covered storm damage for claims.
Photos, repair estimates, past maintenance records, and completed insurance forms are essential for proper documentation.
If you aren’t sure what condition your roof is in, starting with an inspection can give you more information before you decide how to proceed. Midwest works with both insurance-related and out-of-pocket replacement projects.
Midwest offers free consultations for qualifying exterior replacement projects within its service area.
Start by Finding Out What Your Roof Needs
If you started this process unsure whether storm damage should become an insurance claim or an out-of-pocket replacement, that’s normal. You don’t need to have the answer before you speak to a contractor.
Midwest Construction & Remodeling can help you understand your roof's condition and what a full replacement would involve. From there, you’ll have a clearer picture of whether an insurance-related project or a retail replacement makes more sense for your situation.
If recent hail or wind has you questioning your roof’s condition, schedule a consultation. We can help you determine the next step and what a roof damage insurance claim may look like if replacement is warranted.
Essential Roofing Insurance Claim Tips
- Maintain clear communication with your insurance provider at all times.
- Keep detailed records of all interactions and documents related to your claim.
- Understand your policy’s roof insurance deductible before filing any claims.
- Respond promptly to requests from adjusters to avoid claim delays.
- Use technology like roofing insurance software tools for better claims management.
- Prepare thorough roofing repair estimates from licensed contractors to support your claim.
- Learn local insurance regulations to ensure compliance during the claims process.
- After filing a claim, be mindful of potential increases in your insurance premium.
- Use an insurance claim checklist to track all necessary paperwork and steps.
- Seek roofing contractor services that specialize in property restoration post-damage.
How We Support You Through Insurance Claim Timelines
- Streamline inspection scheduling and follow-up tasks efficiently.
- Manage all stages of the roofing replacement insurance process clearly.
- Coordinate between clients, contractors, and insurers for smooth progress.
- Educate clients on what to expect throughout the entire claims journey.
- Help navigate complicated insurance company procedures effectively.
Protect Your Investment with Proper Roofing Materials & Warranty Coverage
- Choose materials that offer strong roofing material insurance coverage against storms.
- Review roofing warranty details thoroughly before installation begins.
- Select durable options suitable for Minnesota storm damage conditions for longevity.
Managing Challenges in Roofing Insurance Disputes
- Know how to engage in effective claims dispute resolution when necessary.
- Utilize professional support to avoid common errors leading to insurance claim denial and roof issues.
Contact Us
Mon-Fri: 7am-8pm
Sat: 9am-5pm
Sun: Closed